

Direct Express® Mobile analysis by Appwee
Managing a prepaid benefit card is rarely something I want to turn into a long banking session. I usually need a quick answer: has a payment gone through, is money available, or did a recent purchase appear correctly? Direct Express® Mobile is built around that practical kind of check-in. It is a free finance app from Fifth Third Bank for people who use a Direct Express® prepaid debit card to receive federal benefits, and its value depends heavily on how reliably it can connect when I need it.
That focus makes it different from a general banking app. I would not install it expecting a complete everyday bank replacement with a broad collection of financial products. I see it more as a mobile companion for keeping an eye on card activity and handling routine account tasks from a phone. For the right cardholder, that narrow purpose can be a strength. For someone looking for budgeting tools, investment accounts, or a full-service checking experience, it is a reason to choose something else.
How Direct Express® Mobile feels when the network is doing the work
The first thing I noticed is that the useful parts of a card-management app depend on current account information. Checking a balance or looking over recent activity is most valuable when the app can reach the service and return up-to-date details. That means a strong mobile signal or dependable Wi-Fi is not just convenient here; it shapes whether the app feels immediate or frustrating.
In a normal morning scenario, I might be standing outside a pharmacy and want to confirm that my available funds cover a purchase before reaching the register. With a stable connection, opening the app and checking the account is much less awkward than trying to remember the last balance or searching through paper records. The benefit is not flashy. It is the confidence of making a small decision with current information.
The same network dependence matters after a card payment. If I am checking whether a transaction has appeared, I want the app to retrieve fresh activity rather than show me an old screen that looks reassuring but may not include the latest purchase. I treat any displayed information as useful only when the app has had a chance to connect successfully. That is an important habit with any financial app, but especially with one centered on a prepaid card balance.
Connectivity can also become a problem at exactly the wrong time. A crowded store, a basement, a rural road, or a weak indoor signal can make a simple account check take longer. I would avoid waiting until the payment terminal is ready to discover whether the app can load. Checking earlier, while I still have a reliable connection, is a small change that makes the experience much smoother.
There is a practical distinction between opening an app and receiving current account information. The phone may launch normally even when the service cannot be reached. I would not interpret a successful launch as proof that the balance or transaction history has refreshed. When the connection is poor, I prefer to wait for a clear update rather than make a financial decision based on information that may be stale.
This is where the app’s narrow purpose helps. I am not navigating a crowded dashboard full of unrelated products while waiting for a card detail to load. The reason for opening it is straightforward. At the same time, that simplicity means every connection problem is more noticeable: if the main task is checking card information, delays directly affect the main task rather than merely slowing down an optional feature.
Useful in short mobile moments
I find this app best suited to brief sessions. A quick check before shopping, a review after an unfamiliar purchase, or a glance at activity while planning the week are more natural uses than sitting down for a long financial review. The phone format fits those moments because the account is available where the decision happens, rather than only at a computer.
That portability is particularly useful for people who do not want to carry account paperwork or rely on memory. A phone can be easier to reach in a shop, at home, or while traveling locally. The app does not turn a prepaid card into a conventional bank account, but it can make the existing card easier to monitor during ordinary errands.
I would still prepare before leaving home if I expected to need account information. A dependable connection at home gives me a chance to review recent activity before heading somewhere with uncertain reception. This is one of the less obvious trade-offs: mobile access is convenient, but convenience is strongest when I use it proactively rather than treating the app as an emergency tool at the exact point of sale.
For a family member helping someone keep track of benefit spending, the app may also make conversations more concrete. Instead of asking someone to estimate what remains, the cardholder can check the account directly and discuss a current figure. I would be careful about sharing login details, though. Convenience should not turn into casual access to another person’s financial information.
Travel introduces another consideration. If I am away from my usual Wi-Fi, I would expect the experience to depend on the quality and availability of mobile data. I would check the account before setting out, keep the phone charged, and avoid assuming that a remote location will offer the same responsiveness as home. Those are simple precautions, but they matter more for a service whose usefulness comes from reaching live account information.
The app is rated for Everyone, which makes its presentation approachable for a broad audience. In practice, ease of use also depends on comfort with phone security, account sign-in, and recognizing legitimate prompts. A clear interface can reduce confusion, but it cannot replace careful habits such as using a private screen in public and keeping the device protected.
What I do when a check fails
When the app does not respond as expected, I start by separating a connection issue from an account issue. I check whether other services load, move from weak cellular reception to trusted Wi-Fi when possible, and try again after the connection settles. This avoids treating a temporary network problem as evidence that something is wrong with the card itself.
I also avoid repeatedly tapping buttons while a request appears to be processing. With financial information, impatience can create confusion: I may not know whether a request failed, is still waiting, or simply needs another moment. I prefer one deliberate retry, followed by a pause, rather than a series of rapid attempts that makes the result harder to interpret.
If a transaction or balance still looks wrong after a successful refresh, I would record the basic details before seeking help: the approximate time, the merchant or activity description, and what the app displayed. That preparation makes a support conversation more useful. It also helps me distinguish a delayed appearance from a genuinely unfamiliar transaction.
A weak connection is not the only possible source of friction. Sign-in problems, a locked account, an outdated app build, or a device setting can interrupt access even when the network works. I would keep the app current and make sure the phone itself is using a supported operating system. The listed minimum is Android or iOS version 9, so devices below that threshold should not be treated as a dependable home for the app.
The current version is 9.4, and that gives me another practical reason to check for updates rather than assuming an old installation will behave identically. Updates can affect compatibility and reliability, but I would install them through the normal official app channel and avoid downloading questionable copies that imitate a financial service.
Recovery is easier when I have a fallback plan. If I cannot connect in a store, I can postpone the purchase decision, use a trusted connection later, or rely on the card’s other established support options rather than repeatedly forcing the app to respond. The important point is that the app should support my decision, not pressure me into spending while I am uncertain about the available balance.
Using it without wasting mobile data
For most people, occasional account checks should be manageable, but I still prefer to be deliberate with mobile data. I would use Wi-Fi for longer sessions or updates when it is secure and trusted, and reserve cellular access for short checks when I am away from home. I would not connect to an unknown public network simply to avoid using a small amount of mobile data; protecting account access matters more than saving a few megabytes.
One useful routine is to review activity in a single session instead of opening the app repeatedly for every small question. If I am planning several errands, I can check the account once before leaving and again afterward to review what changed. That reduces unnecessary loading and gives me a clearer before-and-after picture of spending.
I would also avoid leaving the app open while moving through areas with unstable reception. A screen that remains visible is not the same as a continuously refreshed account. Closing the session and checking again later through a reliable connection is more sensible than assuming that an unchanged display reflects current information.
People with limited data plans should pay attention to the phone’s general update settings as well as this app. The app itself is for account access, but operating-system and app updates can use more data than a quick balance check. Scheduling updates over trusted Wi-Fi is a sensible way to keep the installation current without letting maintenance consume a mobile allowance unexpectedly.
Battery life is part of the same equation. A phone with very little charge is a poor place to depend on a financial check, especially if the connection is weak and the device has to work harder to complete a request. I would check important information before leaving home and keep a charging option available on longer days. That is not a special feature of the app, but it is a realistic part of using any mobile account tool responsibly.
Where it fits among financial alternatives
Compared with a traditional bank app, Direct Express® Mobile is more focused. A full-service banking app may combine checking, savings, transfers, bill payment, card controls, budgeting, and other products in one place. That broader approach is useful for someone managing several types of accounts, but it can also add clutter when the main need is monitoring a Direct Express® card.
Compared with a paper statement or telephone-based account check, the app offers a more convenient way to look at information during the day. The trade-off is that it requires a compatible phone, a working connection, and comfort with digital sign-in. Someone with unreliable internet access or little interest in mobile account management may find a non-app method more dependable.
Compared with a general prepaid-card app, this one makes sense specifically when the underlying card is Direct Express®. I would not choose it simply because I want any prepaid account manager. The card relationship comes first; the app is useful because it belongs to that particular financial arrangement.
The app has attracted a large user base, with over a million installs, and its average rating is 4.6 from around 192 thousand ratings. Those figures suggest that many people find the mobile option worthwhile, but they do not remove the need to judge it against personal circumstances. A high rating cannot fix a weak signal, an unsupported phone, or the mismatch between a focused card app and someone’s desire for broader banking tools.
Its free price is another practical advantage for eligible cardholders who want mobile access without adding an app subscription to their expenses. I still would not confuse “free” with “everything is included in every financial situation.” The app’s role is to help manage the associated prepaid card; it is not a promise of all the services found in a conventional bank relationship.
Fifth Third Bank is the developer, which gives the app a clear connection to the service rather than making it a third-party tracker. Even so, I would install only the legitimate version, verify the app identity before entering account information, and keep normal security habits in place. Financial convenience is valuable only when the access path is trustworthy.
Who should use it and who should look elsewhere
I would recommend Direct Express® Mobile to a Direct Express® cardholder who wants quick access to balance and activity information while away from a computer. It is especially suitable for short, practical checks before or after purchases, provided the person has a supported phone and usually reliable connectivity.
I would be more cautious recommending it to someone whose phone is old, whose internet access is consistently unreliable, or who needs a detailed budgeting system. The app may help that person monitor a card, but it may not address the larger financial need. A separate budgeting tool or a broader banking service could be a better companion, depending on the accounts involved.
I also would not treat it as a replacement for understanding card activity. An app can make information easier to reach, but I still need to recognize expected merchants, notice unusual entries, and act promptly when something does not look familiar. The best workflow is not merely “open the app”; it is “connect, review, compare with what I remember, and respond when necessary.”
After using it as a focused mobile finance tool, my verdict is positive but specific. Its strongest feature is dependable access to Direct Express® card information when the network, phone, and account access are all working together. That makes everyday checks less inconvenient and can remove uncertainty from small spending decisions.
Its main weakness is equally clear: the experience is tied to connectivity and to a narrow card-management purpose. I would not rely on it as my only plan in a place with poor reception, and I would not expect it to replace a complete banking or budgeting platform. For eligible users who want a free, straightforward way to keep track of their prepaid benefit card from a mobile device, it is a sensible choice. For everyone else, the right alternative depends on whether they need broader financial tools or a method that remains practical when internet access is unreliable.
Gallery
Direct Express® Mobile Pros and Cons
- Quickly check your Direct Express card balance and available funds.
- Review recent transactions to monitor spending and spot unauthorized activity.
- Card controls are accessible from a mobile device without visiting an ATM.
- Official app provides a convenient way to manage federal benefit payments.
- Security features help protect access to your card account.
- Some features may require identity verification or additional account details.
- App usefulness is limited if you do not have a Direct Express card.
- Transaction updates may not appear immediately after a purchase.
- Users may need customer support for issues the app cannot resolve.
- Availability and performance can vary depending on device and internet connection.
Direct Express® Mobile Frequently Asked Questions
What is Direct Express® Mobile used for?
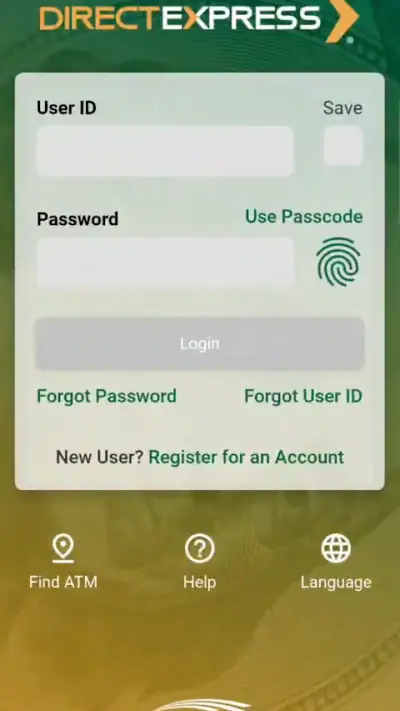
Direct Express® Mobile is the official mobile banking app for eligible Direct Express cardholders. After signing in, users can generally review their available balance, check recent transactions, view deposit information, locate nearby ATMs, and manage selected card settings. It is designed to provide convenient access to account information without needing to call customer service or visit a location.
Who can use the Direct Express® Mobile app?
The app is intended for people who have an active Direct Express card account, commonly used to receive federal benefit payments electronically. You normally need your card or account credentials and other identity-verification details to register or sign in. If you do not have a Direct Express card, the app may not provide useful account access, and eligibility questions should be directed to Direct Express support.
Is Direct Express® Mobile safe to use for checking my benefits and card activity?
The application is built to provide protected access to Direct Express account information and may use login verification, device security, and other safeguards. However, no mobile service is completely risk-free. Install it only from an official app store, keep your phone and operating system updated, avoid sharing passwords or verification codes, and never sign in through links received in suspicious messages.
Can I use the app to withdraw money, transfer funds, or replace my card?
Direct Express® Mobile is primarily intended for viewing and managing card information, but the exact services available can depend on your account status, app version, and current program rules. Features such as ATM-location tools, card controls, reporting a lost card, or requesting assistance may be available, while some transactions or account changes may require customer-service support.
What should I do if Direct Express® Mobile will not let me sign in?
First, check that your internet connection is working and that you are using the latest version of the official app. Carefully re-enter your credentials and follow the available password or account-recovery instructions. Avoid repeated guesses if your account becomes locked. If the problem continues, contact Direct Express through its official customer-service channels, especially if you suspect unauthorized activity.














